News
VENO tv: Business Access Holdings Chairman calls for productive finance, stronger African banks, and deeper continental integration at AFIS 2026
Date: 05-11-26
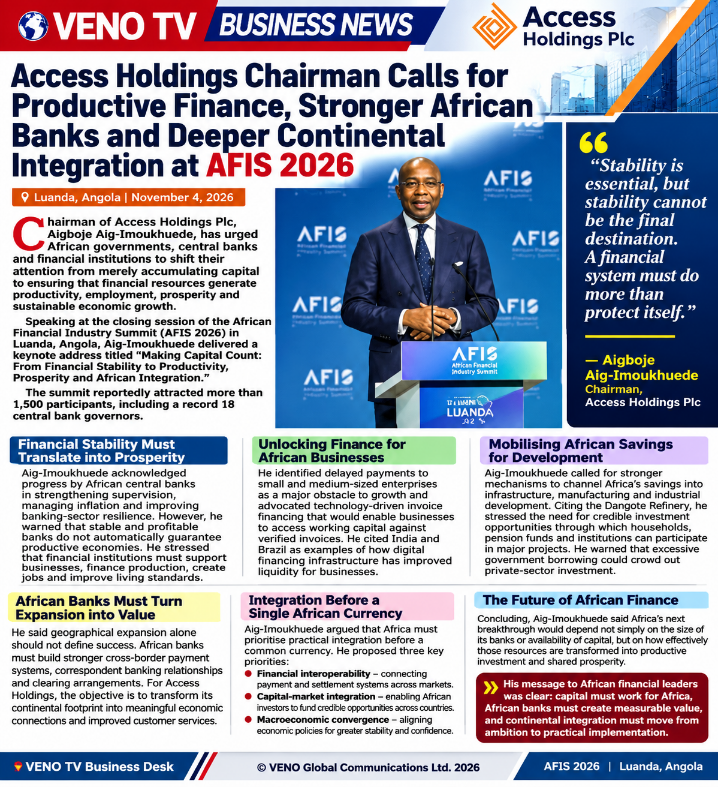
Luanda, Angola – November 4, 2026: Chairman of Access Holdings Plc, Aigboje Aig-Imoukhuede, has challenged African policymakers, central bankers and financial institutions to move beyond measuring progress by the volume, ownership or cost of capital and focus instead on how effectively capital is deployed to create productivity, prosperity and lasting economic value.
Delivering the keynote address at the closing session of the African Financial Industry Summit, AFIS 2026, in Luanda, Aig-Imoukhuede said Africa’s next phase of financial development must convert macroeconomic stability, stronger institutions and indigenous banking capacity into tangible improvements in businesses, communities and people’s lives.
His address, themed “Making Capital Count: From Financial Stability to Productivity, Prosperity and African Integration,” concluded a summit attended by more than 1,500 participants and a reported record 18 central bank governors. He described their participation and collaboration as evidence that Africa was building stronger consensus around the reforms and institutional capabilities required for economic transformation.
However, he warned that capital, resilient banks and macroeconomic stability would not automatically deliver Africa’s required development outcomes. The central question, he said, was whether capital was being deployed productively to create growth, prosperity, and meaningful improvements in people’s lives.
Several African economies, he noted, have made progress in managing inflation, currency volatility, and financial-sector risk. These gains could support growth, but stability must translate into productive investment, enterprise development, and broad-based prosperity.
“Stability is essential, but stability cannot be the final destination,” he said. “A financial system must do more than protect itself. It must support production, enable investment, create opportunities, and help lift people out of poverty.”
Redefining Financial-System Success
Aig-Imoukhuede commended African central banks for strengthening supervision and building more resilient banking systems while addressing inflation, exchange-rate pressures, and other vulnerabilities. Yet a banking system could be stable, profitable, and well regulated while the wider economy remained unproductive.
Africa must therefore broaden its definition of financial-system success. Inflation, capital adequacy, risk ratings, and profitability remain important, but countries must also assess whether financial institutions finance production, support businesses, create jobs, expand productive capacity, and improve living standards.
Unlocking Capital Trapped in Commercial Transactions
The priority, he said, is releasing capital trapped in everyday commercial transactions. Many small and medium-sized enterprises supply goods and services to larger, creditworthy companies, complete their work within 90 to 120 days, but wait much longer for payment.
This cash-flow pressure restricts their ability to pay employees, replenish inventory, accept contracts, and invest in expansion. Africa therefore needs infrastructure that enables SMEs to convert verified invoices into immediate financing, with borrowing costs reflecting the corporate buyer’s credit strength.
Aig-Imoukhuede cited technology-enabled invoicing and invoice-financing models in India and Brazil as examples of how digital systems can improve access to working capital. Turning commercial receivables into financeable assets could release liquidity, strengthen supply chains, support employment, and improve the resilience of productive sectors.
Mobilising African Savings for Productive Investment
The second priority is connecting Africa’s domestic savings with its long-term development needs. Aig-Imoukhuede highlighted the mismatch between commercial banks’ short-term deposits and the long-term funding required for infrastructure, industrial development, and other productive assets.
African households and institutional investors, he said, will invest for the long term when credible opportunities and suitable products exist. Citing the Dangote Refinery, he called for mechanisms enabling households, pension funds, and institutions to participate in major African projects.
Africa cannot remain excessively dependent on foreign capital while domestic savings are concentrated in instruments that do not sufficiently support productive transformation. The continent should create vehicles through which African capital can finance African development at appropriate levels of risk and return, without weakening fiduciary or prudential standards.
Government Borrowing Must Not Crowd Out Business
The third challenge is excessive public-sector borrowing, which can absorb capital that would otherwise finance manufacturers, entrepreneurs, and other productive enterprises. When government securities offer attractive, relatively low-risk returns, financial institutions and investors may have limited incentives to fund more complex private-sector activities.
This could produce a stable financial system disconnected from the productive economy. Aig-Imoukhuede called for stronger coordination between monetary and fiscal authorities, stressing that central banks could not resolve structural challenges through monetary policy alone.
He proposed that future AFIS gatherings include finance and budget ministers alongside central bank governors, enabling fuller discussions about government financing, debt sustainability, private-sector credit, and long-term growth.
African Banks Must Turn Scale into Value
Turning to banking, Aig-Imoukhuede said the expansion of indigenous institutions into markets previously dominated by international banks was significant, especially as some global players reduced or exited African operations. However, African ownership and geographical expansion were not sufficient measures of success.
African banks must match or exceed the services previously provided by global institutions. This requires robust cross-border payment systems, international clearing arrangements, correspondent banking relationships, and operational capabilities that connect African customers to regional and global markets.
Speaking about Access Bank’s presence in Angola, he said the ambition must extend beyond a successful domestic bank. It must provide customers with the international capabilities and connectivity required to compete globally. African banks should build relationships in leading international financial centres, including Group of Seven markets, and develop clearing, payment, and settlement infrastructure for cross-border business.
For Access Holdings, this reflects the transition from scale to value. Its footprint must increasingly be measured by the strength of connections it creates, service quality, franchise productivity, and contribution to cross-border economic activity. A pan-African institution’s value lies not simply in the number of countries where it operates, but in its ability to make those markets work better together.
Integration Must Come Before a Common Currency
Aig-Imoukhuede also challenged the tendency to reduce African integration to the creation of a single currency. Before considering monetary union, Africa must achieve practical integration across its markets, financial systems, goods, services, and people.
He illustrated persistent mobility barriers by recounting how his chief of staff could not accompany him to Angola because of visa difficulties. The experience, he said, exposed the contradiction between Africa’s integration ambitions and restrictions that continue to obstruct Africans’ movement across the continent.
Financial integration requires greater mobility, accessible regional markets and interoperable infrastructure, enabling capital and businesses to move efficiently across borders and citizens to participate more freely in opportunities beyond their own countries.
Three Priorities for African Integration
Aig-Imoukhuede proposed three priorities. First is financial interoperability through connected infrastructure for secure, efficient cross-border payments, settlements, and services. Fragmented systems increase business costs, delay transactions, and impede intra-African trade.
Second is capital-market integration, enabling investors, pension funds, and institutions in one country to access credible opportunities elsewhere in Africa. This could expand funding for businesses and infrastructure while providing investors with a wider range of productive assets.
Third is macroeconomic convergence. Deeper financial integration will require greater alignment of economic policies and conditions, creating the confidence and consistency needed for capital, institutions, and businesses to operate effectively across borders.
In conclusion, Aig-Imoukhuede said the next frontier for Africa’s financial institutions is not expansion for its own sake, but converting scale into value through stronger connectivity, productive investment, and measurable economic impact.
Date: 05-11-26
Luanda, Angola – November 4, 2026: Chairman of Access Holdings Plc, Aigboje Aig-Imoukhuede, has challenged African policymakers, central bankers and financial institutions to move beyond measuring progress by the volume, ownership or cost of capital and focus instead on how effectively capital is deployed to create productivity, prosperity and lasting economic value.
Delivering the keynote address at the closing session of the African Financial Industry Summit, AFIS 2026, in Luanda, Aig-Imoukhuede said Africa’s next phase of financial development must convert macroeconomic stability, stronger institutions and indigenous banking capacity into tangible improvements in businesses, communities and people’s lives.
His address, themed “Making Capital Count: From Financial Stability to Productivity, Prosperity and African Integration,” concluded a summit attended by more than 1,500 participants and a reported record 18 central bank governors. He described their participation and collaboration as evidence that Africa was building stronger consensus around the reforms and institutional capabilities required for economic transformation.
However, he warned that capital, resilient banks and macroeconomic stability would not automatically deliver Africa’s required development outcomes. The central question, he said, was whether capital was being deployed productively to create growth, prosperity, and meaningful improvements in people’s lives.
Several African economies, he noted, have made progress in managing inflation, currency volatility, and financial-sector risk. These gains could support growth, but stability must translate into productive investment, enterprise development, and broad-based prosperity.
“Stability is essential, but stability cannot be the final destination,” he said. “A financial system must do more than protect itself. It must support production, enable investment, create opportunities, and help lift people out of poverty.”
Redefining Financial-System Success
Aig-Imoukhuede commended African central banks for strengthening supervision and building more resilient banking systems while addressing inflation, exchange-rate pressures, and other vulnerabilities. Yet a banking system could be stable, profitable, and well regulated while the wider economy remained unproductive.
Africa must therefore broaden its definition of financial-system success. Inflation, capital adequacy, risk ratings, and profitability remain important, but countries must also assess whether financial institutions finance production, support businesses, create jobs, expand productive capacity, and improve living standards.
Unlocking Capital Trapped in Commercial Transactions
The priority, he said, is releasing capital trapped in everyday commercial transactions. Many small and medium-sized enterprises supply goods and services to larger, creditworthy companies, complete their work within 90 to 120 days, but wait much longer for payment.
This cash-flow pressure restricts their ability to pay employees, replenish inventory, accept contracts, and invest in expansion. Africa therefore needs infrastructure that enables SMEs to convert verified invoices into immediate financing, with borrowing costs reflecting the corporate buyer’s credit strength.
Aig-Imoukhuede cited technology-enabled invoicing and invoice-financing models in India and Brazil as examples of how digital systems can improve access to working capital. Turning commercial receivables into financeable assets could release liquidity, strengthen supply chains, support employment, and improve the resilience of productive sectors.
Mobilising African Savings for Productive Investment
The second priority is connecting Africa’s domestic savings with its long-term development needs. Aig-Imoukhuede highlighted the mismatch between commercial banks’ short-term deposits and the long-term funding required for infrastructure, industrial development, and other productive assets.
African households and institutional investors, he said, will invest for the long term when credible opportunities and suitable products exist. Citing the Dangote Refinery, he called for mechanisms enabling households, pension funds, and institutions to participate in major African projects.
Africa cannot remain excessively dependent on foreign capital while domestic savings are concentrated in instruments that do not sufficiently support productive transformation. The continent should create vehicles through which African capital can finance African development at appropriate levels of risk and return, without weakening fiduciary or prudential standards.
Government Borrowing Must Not Crowd Out Business
The third challenge is excessive public-sector borrowing, which can absorb capital that would otherwise finance manufacturers, entrepreneurs, and other productive enterprises. When government securities offer attractive, relatively low-risk returns, financial institutions and investors may have limited incentives to fund more complex private-sector activities.
This could produce a stable financial system disconnected from the productive economy. Aig-Imoukhuede called for stronger coordination between monetary and fiscal authorities, stressing that central banks could not resolve structural challenges through monetary policy alone.
He proposed that future AFIS gatherings include finance and budget ministers alongside central bank governors, enabling fuller discussions about government financing, debt sustainability, private-sector credit, and long-term growth.
African Banks Must Turn Scale into Value
Turning to banking, Aig-Imoukhuede said the expansion of indigenous institutions into markets previously dominated by international banks was significant, especially as some global players reduced or exited African operations. However, African ownership and geographical expansion were not sufficient measures of success.
African banks must match or exceed the services previously provided by global institutions. This requires robust cross-border payment systems, international clearing arrangements, correspondent banking relationships, and operational capabilities that connect African customers to regional and global markets.
Speaking about Access Bank’s presence in Angola, he said the ambition must extend beyond a successful domestic bank. It must provide customers with the international capabilities and connectivity required to compete globally. African banks should build relationships in leading international financial centres, including Group of Seven markets, and develop clearing, payment, and settlement infrastructure for cross-border business.
For Access Holdings, this reflects the transition from scale to value. Its footprint must increasingly be measured by the strength of connections it creates, service quality, franchise productivity, and contribution to cross-border economic activity. A pan-African institution’s value lies not simply in the number of countries where it operates, but in its ability to make those markets work better together.
Integration Must Come Before a Common Currency
Aig-Imoukhuede also challenged the tendency to reduce African integration to the creation of a single currency. Before considering monetary union, Africa must achieve practical integration across its markets, financial systems, goods, services, and people.
He illustrated persistent mobility barriers by recounting how his chief of staff could not accompany him to Angola because of visa difficulties. The experience, he said, exposed the contradiction between Africa’s integration ambitions and restrictions that continue to obstruct Africans’ movement across the continent.
Financial integration requires greater mobility, accessible regional markets and interoperable infrastructure, enabling capital and businesses to move efficiently across borders and citizens to participate more freely in opportunities beyond their own countries.
Three Priorities for African Integration
Aig-Imoukhuede proposed three priorities. First is financial interoperability through connected infrastructure for secure, efficient cross-border payments, settlements, and services. Fragmented systems increase business costs, delay transactions, and impede intra-African trade.
Second is capital-market integration, enabling investors, pension funds, and institutions in one country to access credible opportunities elsewhere in Africa. This could expand funding for businesses and infrastructure while providing investors with a wider range of productive assets.
Third is macroeconomic convergence. Deeper financial integration will require greater alignment of economic policies and conditions, creating the confidence and consistency needed for capital, institutions, and businesses to operate effectively across borders.
In conclusion, Aig-Imoukhuede said the next frontier for Africa’s financial institutions is not expansion for its own sake, but converting scale into value through stronger connectivity, productive investment, and measurable economic impact.
LINKS
- VENO NEWS Don't Be Carried Away By Rallies -Okotie Warns- VENO NEWS: EXPOSED! FEDERAL POLYTECHNIC ADO EKITI's MANAGEMENT TEAM IN ALLEGED FRAUD SCANDAL, DRAGGED TO SPECIAL FRAUD UNIT, RELEASED!
- VENO NEWS:Behold The Newly Fulfilled Prophecies Of Primate Elijah Ayodele
- VENO NEWS: Yes! Time To Recover Nigeria: ‘He’s The Best Option’ — Dogara, Northern Religious Leaders Endorse Atiku
- VENO NEWS:GENESIS GLOBAL HOLDS 2022 ANNUAL HARVEST TAGGED HARVEST OF STRANGE MERCY
- VENO NEWS: 2023 PRESIDENCY: Atiku Abubakar Meets With Aliko Dangote, Jim Ovia, Other Private Sector Leaders.
- VENO NEWS: Okotie: The Face Of Restructuring By Ladi Ayodeji VENO NEWS: Okotie: The Face Of Restructuring By Ladi Ayodeji
- VENO NEWS: THE 61ST FIRSTBANK LAGOS AMATEUR OPEN GOLF CHAMPIONSHIP TEES OFF THIS FRIDAY
- VENO NEWS: Two Years After: WIFE Of late Trado-medical Practitioner, Oko Oloyun Remarries
- VENO NEWS:FBNBANK UK STANDS TALL AT 40, APPRECIATES ITS CUSTOMERS AND REGULATORS
- VENO NEWS: Weekend Delight: If Your Motivational Force Believes In You, Your Success is Fully Guaranteed. Godday Odidi
- VENO NEWS: PCC Chairman, Otunba Kunle Folarin Is Dead
- VENO NEWS: FRSC DOES NOT USE POINT OF SALE (POS) MACHINES NOR RECEIVE PAYMENT FOR FINES FOR TRAFFIC OFFENCES BOOKED ON PATROL POINTS
- VENO NEWS: BUHARI CONGRATULATES FBN ON 40 YEARS OF CROSS - BORDER BANKING IN UK
- VENO NEWS: Okotie Faults Presidential Candidates' Campaign Promises
- VENO NEWS:FIRSTBANK SPONSORS FIFTH CHUKKER AFRICAN PATRONS CUP POLO TOURNAMENT
- VENO NEWS: Okotie To Buhari: Restructuring Will Be Your Greatest Legacy
- VENO NEWS: Primate Ayodele, Dr. Ayodele, Pastor Bamiduro, Olukere Back Veno Praise Night
- VENO NEWS:Lessons From Truss' Resignation -Okotie
- VENO NEWS: FirstBank Boosts The Business Operations Of Its Customers With A Bouquet Of Retail Product Offerings
[First Page] [Prev] Page 53 of 71 [Next] [Last Page]